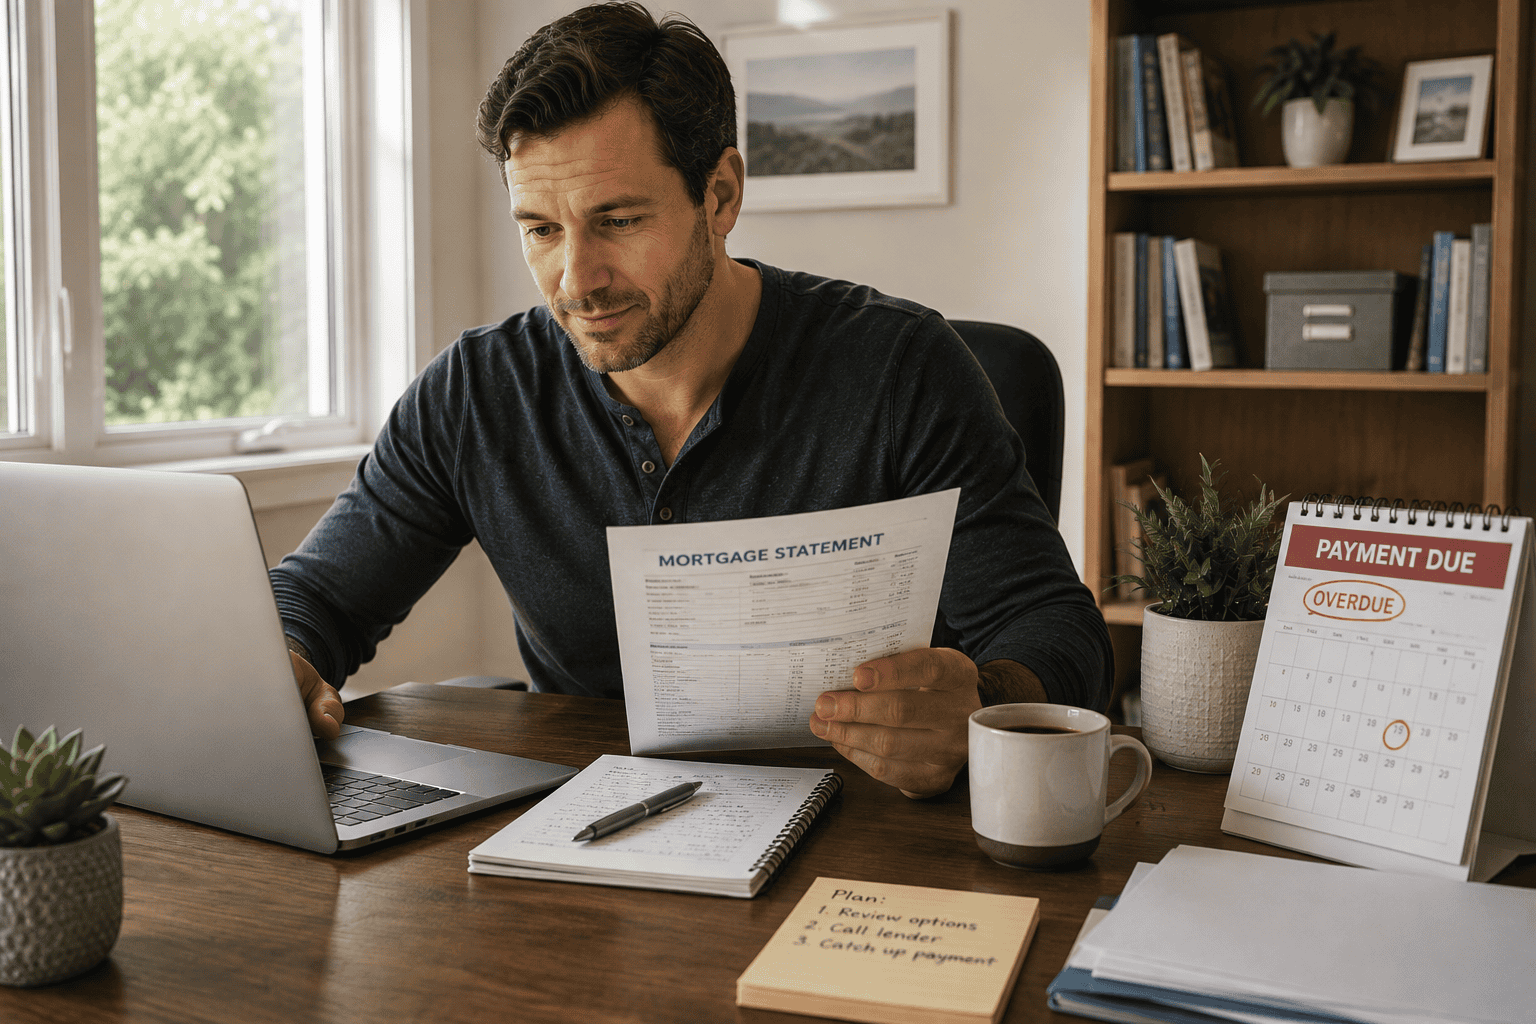


Using a second mortgage to fix your credit is one of the most practical ways a homeowner can turn a difficult situation around. If you own a property with equity built up in it, you can borrow against that equity to clear high-interest debt, catch up on what you have fallen behind on, and give your credit room to recover. At Turnedaway.ca we arrange second mortgages for Ontario homeowners the banks decline, based on your home equity rather than your credit score.
How to Use a Second Mortgage to Fix Your Credit
The most common way a second mortgage to fix your credit works is through debt consolidation. Instead of juggling several high-interest balances, credit cards, store cards, unsecured lines of credit, you roll them into one lower-rate payment secured against your home. That does two things: it simplifies your month, and it lowers the balances that drag your credit score down. As those balances come down and payments stay on track, your credit naturally starts to recover.
How a Second Mortgage Works
A second mortgage is a loan secured against your home that sits behind your existing first mortgage, so you keep your first mortgage exactly as it is. It is similar to a home equity loan: you borrow against the equity you have built up, generally up to 80% of your home’s value, combining your first mortgage and the new second mortgage together.
Many homeowners choose a second mortgage over refinancing to avoid the penalty for breaking their first mortgage, and because approval is based on your equity rather than your credit rating or income. It is often more straightforward to qualify for than a refinance. Common uses include:
- Catching up on missed mortgage payments
- Clearing CRA arrears
- Stopping a power of sale
- Eliminating property tax arrears
- Consolidating high-interest credit card debt
A second mortgage carries a much lower rate than credit cards and can be arranged quickly, with approvals often within 24 to 48 hours when you work with a broker who specializes in them.
What If I Have Bad Credit?
Bad credit does not automatically shut the door. The big banks may decline higher-risk files regardless of how much equity you hold, but you still have options. The key is a mortgage broker who specializes in credit-challenged files and works with lenders beyond the banks, including alternative lenders, mortgage investment corporations, trust companies, credit unions, and private lenders.
These lenders do not lead with your credit score. They look at the marketability of your home and how much equity you have built up, and they approve on common sense, knowing life throws people curveballs. If your credit is bruised, an experienced broker opens doors a bank never will. See our bad credit mortgage solutions.
How Turnedaway.ca Can Help
Want to clear your debt and get your credit back on track? With over 30 years of experience and access to one of Canada’s largest networks of second-mortgage lenders, Turnedaway.ca helps homeowners the banks turned away, at the best rates and most flexible terms we can find. Remember, your equity is the key to approval, not your credit or income. Call us toll-free for a free consultation at 1-855-668-3074 or apply online today.
Frequently Asked Questions
Can a second mortgage to fix your credit actually work?
Yes. Using a second mortgage to consolidate high-interest debt lowers the balances that drag your credit score down. As those balances fall and your payments stay on track, your credit can steadily recover.
How much can I borrow?
Approval typically stays within 80% of your home’s value, combining your first mortgage and the new second mortgage. The more equity you have above that, the more you can access.
Can I qualify with bad credit?
Often yes. Approval is based mainly on your home equity rather than your credit score, so missed payments, collections, and past credit issues do not automatically disqualify you.